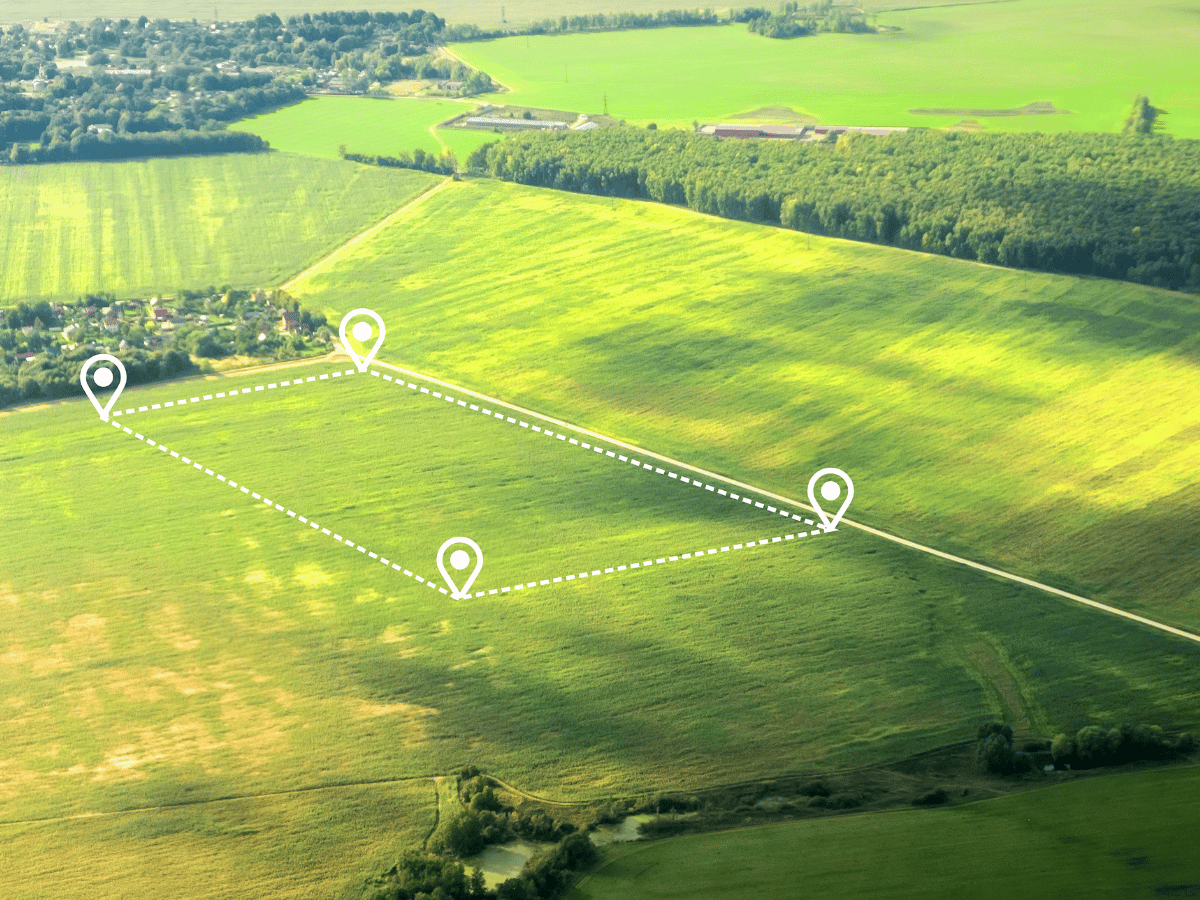
Loans for agriculture land work very differently from standard home loans. Buying farmland, a hobby farm or a rural block means lenders look closely at zoning, land size, intended use and income type. Fewer banks offer rural lending, and their policies vary widely.
This guide explains how loans for agriculture land work and shares seven powerful tips to help you get approved with confidence.
What Are Loans for Agriculture Land?
Loans for agriculture land are finance products designed for rural, regional and semi-rural properties. They can cover vacant land, established farms, hobby farms and lifestyle acreage, and they sit within the wider world of rural finance, which also includes equipment finance, working capital and refinancing.
Unlike a metropolitan home loan, agricultural lending looks closely at what the land is and how you’ll use it. A lender may see a 10-acre lifestyle block very differently from a 500-acre working farm, even when the purchase price is similar. For wider industry background, the Australian Government Department of Agriculture, Fisheries and Forestry is a useful resource.
Types of Loans for Agriculture Land
The right loan depends on your plans for the property. The main options include:
- Rural land and property loans: for buying vacant land or an established rural property.
- Hobby farm loans: for buyers who want to run livestock or grow produce without operating a large commercial farm.
- Agribusiness farm loans: for working farms generating commercial income, often arranged through specialist agribankers.
- Refinancing: restructuring existing rural debt, or consolidating adjoining titles into one facility.
- Equipment and machinery finance: for tractors, vehicles and other farm assets, often arranged alongside the land loan.
- Regional first home buyer loans: for first-time buyers purchasing in rural or regional areas.
What Lenders Assess When Approving Loans for Agriculture Land
Because rural property can be harder to value and slower to sell, lenders assess risk more conservatively. Expect them to consider:
- Zoning: rural, primary production and lifestyle zones can each affect eligibility.
- Land size: many lenders cap the acreage they will accept.
- Property use: lifestyle, hobby farming and commercial farming are assessed differently.
- Income: PAYG, self-employed or farming income must be clearly evidenced.
- Valuation: rural valuations are often conservative, which can affect how much you can borrow.
7 Powerful Tips to Secure Loans for Agriculture Land
1. Check zoning before you fall in love with a property. Land zoned RU1 (Primary Production) is often assumed by banks to be commercial security, even when it’s used as a home. Some lenders assess actual use rather than the zoning label alone. You can look up a property’s zoning on the NSW Planning Portal.
2. Confirm dwelling entitlement. This is whether a block is legally approved to have a house on it. Without it, some lenders treat the property as vacant land, which can raise your deposit and narrow your options for loans for agriculture land.
3. Prepare a larger deposit. Many rural loans require around 20 to 30 per cent, while vacant land can require 20 to 50 per cent depending on size, zoning and location. First home buyers may have extra support through Housing Australia, although zoning and land size restrictions can apply.
4. Be clear about how you’ll use the land. Hobby farms are often assessed more like residential lending, while working farms may need agribusiness-specific finance. Getting this classification right can affect both your options and your rate.
5. Know your numbers. Understand your borrowing capacity, repayments and buffers before you commit. ASIC’s free MoneySmart tools are a good starting point for calculators and guidance.
6. Get finance advice before you make an offer. Checking zoning, dwelling entitlement, likely LVR and lender appetite up front avoids unpleasant surprises after a valuation.
7. Work with a specialist rural broker. Many buyers are knocked back by their regular bank even with a strong income and deposit, simply because the property doesn’t fit standard residential criteria. A broker who understands loans for agriculture land knows which lenders genuinely work with acreage, rural zoning and farming income.
How a Specialist Broker Helps With Agricultural Land Finance
At Rivendell Rural Finance, we help clients with properties from 1 acre to 10,000 acres across NSW, VIC and QLD, with a particular focus on Canberra and surrounds, the Southern Highlands, the Hunter Valley and Northern NSW. We also assist with rural and acreage finance Australia-wide for the right deal.
A broker can compare lender policies on land size and valuations, structure loans around seasonal farm income, advise on using equity versus keeping securities separate, and arrange bridging finance when your sale and purchase settlements don’t line up. Lower-value rural properties, typically under $150,000 to $200,000, may also need a specialist lender rather than a mainstream bank.
Frequently Asked Questions About Loans for Agriculture Land
Can I get a loan for vacant agricultural land?
Yes, though lenders see vacant land as higher risk, so expect a larger deposit than for a property with an existing home.
Are loans for agriculture land harder to get than a standard home loan?
Generally, yes. Fewer lenders offer rural finance, and valuation and zoning rules are stricter. A specialist broker improves your chances by matching you with the right lender from the start.
Ready to Secure Your Loans for Agriculture Land?
Loans for agriculture land don’t have to be stressful when you have the right guidance. Whether you’re eyeing a small acreage, a hobby farm or a large working property, early advice on zoning, deposit and lender choice can save you time and help you secure a loan that fits your plans.
To talk through your purchase, contact the Rivendell Rural Finance team on 1300 653 200 or visit rivendellruralfinance.com.au to start the conversation.